Category: Microgrids

  • The Fuel-Cell Opportunity Is Growing. Can Manufacturing Keep Up?

    The expansion of AI data centers is putting pressure on electricity systems that were not designed to connect large new loads quickly. That is creating interest in on-site power, including fuel cells.

    A Reuters report published October 23 cited Rystad Energy’s projection that investment in fuel cells for data centers could grow from approximately $2.8 billion in 2025 to $30 billion in 2030. Rystad also estimates that about 40% of projected U.S. data-center capacity in 2030 could pursue dedicated on-site power rather than rely entirely on the grid. These are forecasts, not guarantees of investment or deployment. 

    Why data-center developers are considering fuel cells

    Data centers need dependable electricity for computing equipment and cooling. Reuters reports that large U.S. grid connections can take three to six years, according to Rystad estimates. That delay has developers looking at power options that could be installed at or near a facility while grid infrastructure catches up. 

    A fuel cell produces electricity through a chemical reaction involving fuel and oxygen. Natural gas is one current fuel option; some systems can also use hydrogen or hydrogen blends. Because fuel cells generate electricity without combustion inside the stack, they can have lower local emissions than conventional gas-fired generation. That does not make every fuel-cell installation carbon-free: the emissions picture depends on the fuel and its supply chain. 

    Fuel cells may support a data center’s power strategy, but they do not eliminate the need for grid access or other infrastructure. Depending on the project, developers still need fuel connections, permits, transformers, switchgear, and site work. Those requirements can become schedule constraints of their own. 

    Demand growth raises a manufacturing question

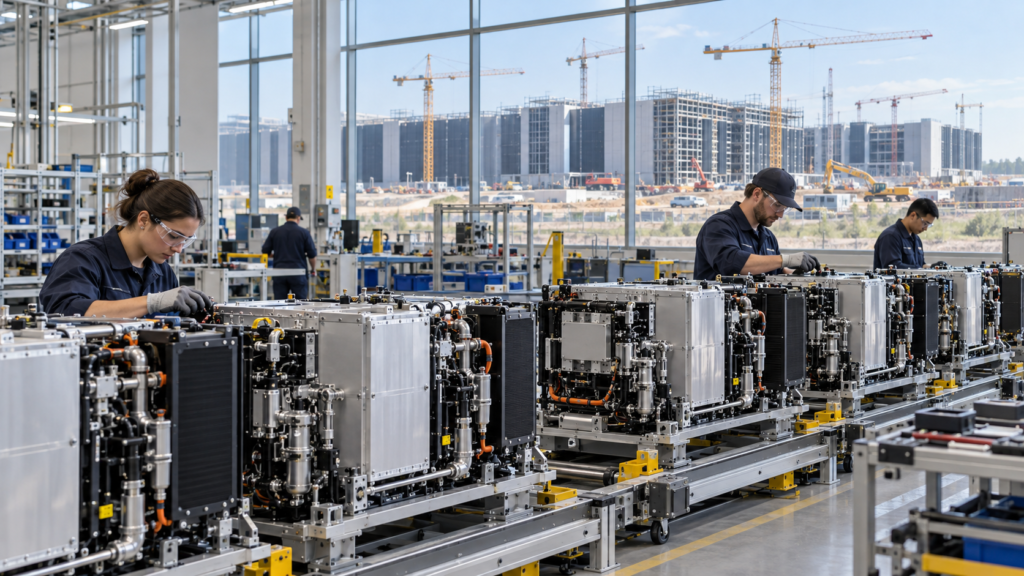
    Rystad estimates annual fuel-cell manufacturing capacity at about 1.8 GW today, potentially increasing to 4 GW by 2030 as manufacturers expand. Rystad also projects 10.4 GW of cumulative fuel-cell demand from data centers between 2026 and 2030. These figures describe different measures—annual production capacity and cumulative demand—so they should not be treated as a direct one-to-one comparison. Together, they show why supply-chain execution deserves attention alongside market growth. 

    The order book also calls for careful reading. Rystad estimates it at roughly 9 GW, including agreements involving large companies. Reuters cautions that framework agreements do not necessarily represent firm orders for the full stated capacity. A headline number can signal interest without confirming exactly how much equipment will be purchased, manufactured, and installed. 

    Scaling production is more than adding factory floor space. It involves securing materials and components, expanding supplier capacity, controlling costs, and maintaining quality as output rises. Rystad has also identified potential material-supply exposure for some solid-oxide fuel-cell designs, another reminder that growth depends on the supply chain behind the finished system. 

    The opportunity depends on delivered power

    For executives, manufacturers, and infrastructure investors, the useful question is not just how large the market forecast looks. It is whether the industry can turn demand into projects that are financed, supplied, permitted, connected to fuel, and ready to operate.

    That creates opportunities across several layers: fuel-cell manufacturing, component supply, gas infrastructure, electrical equipment, project engineering, commissioning, and site development. It also creates risks if any one of those layers scales more slowly than demand.

    The fuel-cell market may grow rapidly. The test will be whether manufacturing capacity and project readiness can grow with it—and whether the economics work at the level of the complete power system.

    Executive takeaway: In the race to power AI, a faster-to-deploy generation technology still depends on factories, materials, fuel, electrical equipment, and a buildable site.

    Entrepreneur question: Which part of the fuel-cell value chain looks most likely to become the next constraint?

    Sources: Reuters, October 23, 2026⁠ · Rystad Energy market analysis⁠

  • AI Data Centers Are Beginning to Bring Their Own Power

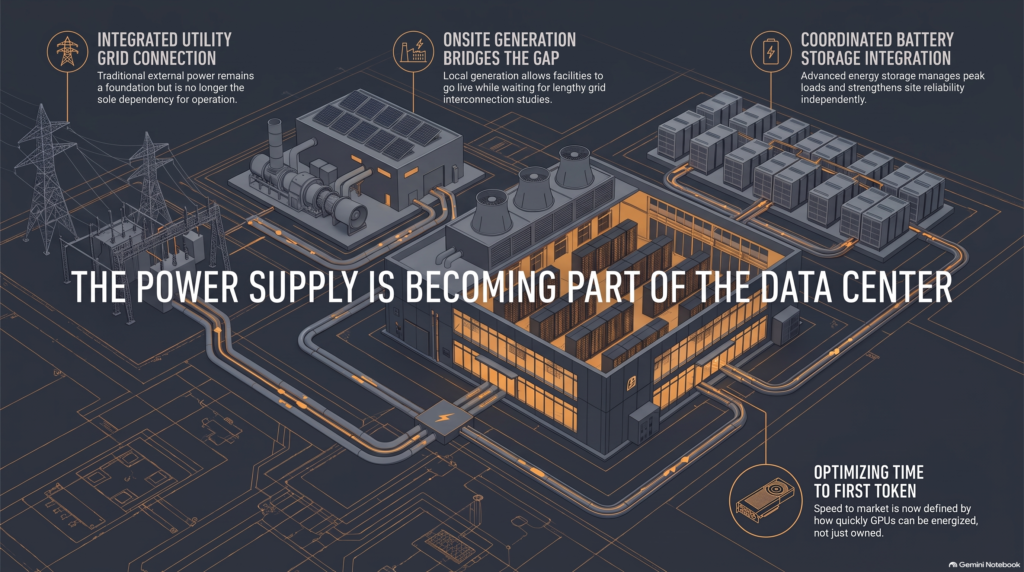
    The power supply is becoming part of the data center.

    The artificial-intelligence infrastructure race is producing an important shift in how data centers are designed.

    For years, developers could treat electricity largely as an external utility service. They selected a location, applied for a grid connection and built the facility around the expectation that sufficient power would eventually arrive.

    That model is becoming less dependable.

    AI data centers require enormous amounts of electricity, often concentrated within a relatively small geographic area. At the same time, utilities must contend with transmission constraints, transformer shortages, lengthy interconnection studies and project requests that may be speculative or duplicated.

    The result is a widening gap between having plans for a data center and having the power required to operate one.

    A $2.6 Billion Signal

    Vertiv has agreed to acquire UtilityInnovation Group, a company specializing in microgrids, advanced power controls and behind-the-meter power architecture for data centers.

    The agreement calls for approximately $1.45 billion in cash at closing, with as much as $1.15 billion in additional payments tied to future earnings targets. That places the potential transaction value at approximately $2.6 billion.

    The acquisition is expected to add microgrid controls, onsite-generation orchestration, specialized switchgear and energy-storage integration to Vertiv’s existing power and cooling portfolio.

    That is more than a routine expansion of product offerings.

    It is evidence that power availability is moving upstream into the earliest stages of data-center planning.

    Vertiv describes the expanded architecture as extending from the utility interconnection to the chip. Its stated objective is to support grid-connected facilities, bridge-to-grid projects and sites capable of operating independently through onsite generation.

    In other words, the power supply is becoming part of the data center itself.

    Why Waiting for the Grid Is Becoming a Competitive Risk

    A developer may control the land, secure financing and purchase computing equipment, yet remain unable to bring the facility online because the local grid cannot supply the requested load.

    That delay carries serious consequences.

    Equipment can sit idle. Construction schedules can slip. Customer commitments can be missed. Capital remains tied up in infrastructure that is not producing usable computing capacity.

    For AI companies, this creates a direct connection between energy availability and speed to market.

    The competitive metric is no longer merely how many GPUs a company owns. It is how quickly those GPUs can be converted into operational compute.

    The industry increasingly describes this as “time to power” or “time to first token.”

    Both phrases point to the same underlying reality: compute capacity does not exist in a commercially meaningful sense until it can be energized.

    What a Microgrid Changes

    A microgrid can coordinate multiple sources of electricity within a defined site or operating area. Depending on its design, it may combine utility service with onsite generation, battery storage and advanced control systems.

    This creates several possible operating models.

    A grid-connected data center can use onsite resources to strengthen reliability or manage peak loads.

    A bridge-to-grid facility can begin operating with onsite generation while waiting for a larger utility connection.

    An islanded facility can operate independently when utility power is unavailable or insufficient.

    These options do not make the traditional grid irrelevant. Large data centers may still require substantial utility service over the long term.

    What changes is the developer’s dependence on a single delivery timeline.

    Instead of waiting passively for the grid to expand, the project can be designed around a coordinated portfolio of energy sources.

    Power Architecture Is Now Data-Center Architecture

    This shift has consequences beyond electrical engineering.

    Site selection must account for access to natural gas, renewable resources, storage capability and future utility interconnection—not merely available land.

    Financing must cover generation and energy infrastructure as well as buildings, cooling and computing hardware.

    Operating plans must address fuel availability, emissions, maintenance, cybersecurity and the interaction between onsite systems and the surrounding grid.

    Regulators and communities will also have questions about who absorbs the cost, risk and environmental impact of these facilities.

    Bringing your own power does not eliminate infrastructure constraints. It relocates and redistributes them.

    A microgrid can reduce dependence on the utility queue, but the project still needs credible equipment, fuel, permits, controls and operating capability. The bottleneck may move from grid interconnection to turbine availability, gas supply, emissions approval or energy-storage procurement.

    There is no magic extension cord hiding behind the data center.

    A New Test of Project Readiness

    The move toward onsite power could also make the distinction between declared demand and observed readiness more visible.

    A speculative developer may submit a large electricity request to preserve a position in the grid queue.

    An execution-ready developer can demonstrate site control, financing, equipment commitments, a credible load schedule and an integrated power plan.

    One has declared demand.

    The other has evidence of deployment readiness.

    That distinction will matter as utilities, investors and regulators decide which projects deserve scarce infrastructure capacity.

    The Larger Signal

    Vertiv’s proposed acquisition suggests that energy infrastructure is no longer an adjacent concern for the data-center industry. It is becoming part of the core technology stack.

    The emerging architecture is not simply:

    Grid → Data center → Servers

    It is becoming:

    Grid + onsite generation + storage + controls → operational compute

    That creates opportunities for microgrid developers, equipment manufacturers, energy-management platforms, project financiers and specialists capable of coordinating infrastructure across traditional industry boundaries.

    It also changes the competitive landscape.

    The next generation of AI infrastructure leaders may not be the companies that merely reserve the largest amount of electricity. They may be the companies that can prove they possess an executable path from site selection to energized compute.

    The power queue is not disappearing.

    But the most serious developers are beginning to engineer their way around it.